Industrial Property Loans | REIF® Loans
Industrial Property Loans for Warehouses and Distribution Assets
At REIF Loans, we provide industrial property loans designed to help investors and developers finance warehouses, light industrial buildings, and logistics centers.
Our lending programs support both acquisition and refinance strategies, offering flexible terms, DSCR-based underwriting, and customized structures that align with your operational goals.
Whether you’re expanding your industrial portfolio, repositioning a property, or refinancing for better terms, REIF Loans helps you secure the capital you need with clarity and confidence.
What Are Industrial Property Loans?
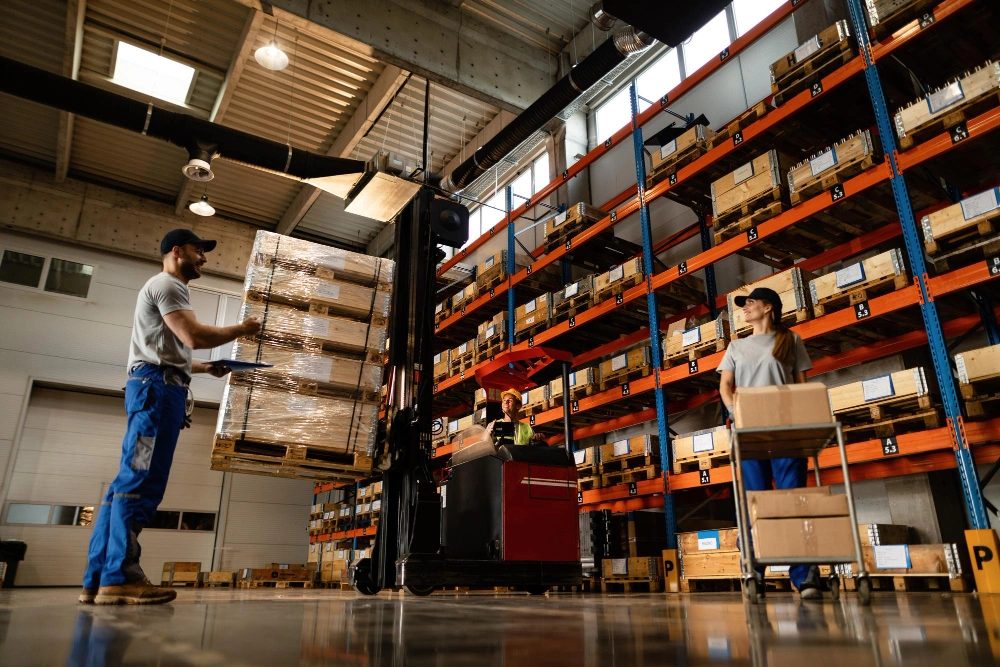
Industrial property loans are commercial real estate loans that finance properties used for manufacturing, storage, or logistics purposes.
They’re ideal for investors, developers, and business owners who manage or lease warehouses, light industrial buildings, and distribution centers.
Typical loan structures include:
These loans prioritize income-producing potential and tenant stability, rather than personal financials.
- Acquisition or refinance loans for owner-user or investment properties
- Bridge financing for value-add or transitional assets
- DSCR-based underwriting focused on property cash flow
- Fixed, floating, or hybrid interest rate options
- Loan terms from 5 to 30 years depending on property type
- SBA 504 for owner-users - as little as 10% down when the business occupies 51% or more
- Financial institutions, life company, and CMBS execution for stabilized $5M-$10M loans
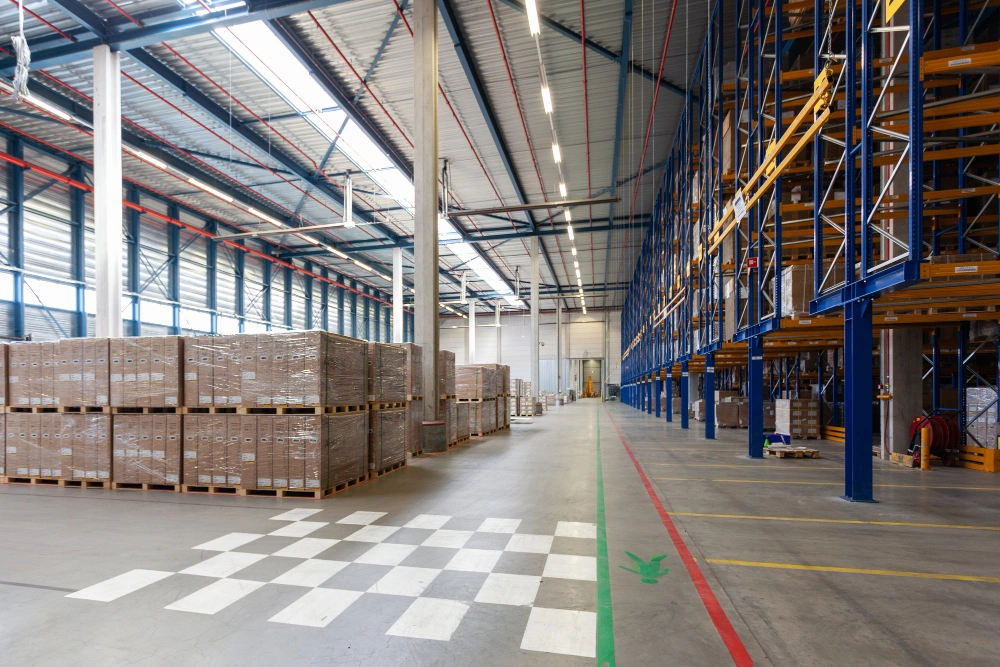
Warehouse Loan Programs for Investors and Operators
A warehouse loan provides flexible capital for purchasing, refinancing, or expanding storage and logistics properties.
REIF Loans structures warehouse financing around occupancy, lease terms, and long-term investment goals.
Stabilized Warehouse Loans
For fully leased, income-generating assets with predictable tenant income.
Bridge Warehouse Financing
Short-term loans for repositioning or improving underutilized properties before refinancing into long-term structures.
Owner-Occupied Warehouse Loans
Designed for businesses buying or refinancing their own facility, with SBA 504 financing available with as little as 10% down (the business must occupy at least 51%).
Portfolio Refinance Solutions
Combine multiple warehouse or industrial assets into a single, efficient financing structure.
DSCR Industrial Loans and Cash Flow-Based Qualification
Our DSCR industrial loans simplify qualification by focusing on property income and operational strength instead of tax returns or personal income verification.
Understanding DSCR for industrial properties:
DSCR (Debt Service Coverage Ratio) = Net Operating Income divided by Annual Debt Payments
A ratio of 1.25x or greater typically qualifies for favorable rates, signaling strong property cash flow.
Benefits of DSCR Industrial Loans:
- Faster approvals and simplified underwriting
- Ideal for leased or income-producing industrial assets
- Works for single-tenant and multi-tenant structures
- Long-term amortization options for improved cash flow
At $5 million and up, lenders size a loan by DSCR, Debt Yield, and LTV, then fund the lowest of the three.
Industrial Property Loan Requirements and Terms
Lenders evaluate property performance, occupancy, and lease structure to determine eligibility and pricing for industrial loans.
Typical qualification criteria include:
- Credit Score: 660+ (700+ preferred)
- LTV: 65%-75% for stabilized properties
- DSCR: Minimum 1.25x–1.35x depending on asset type
- Occupancy: 80–100% preferred for long-term loans
- Tenant Type: National, regional, or stable local operators preferred
- Lease Term: 3–10 years with renewal options
- Loan Term: 5–30 years, fixed or hybrid structures available
We work closely with investors and operators to match the right financing structure to each property’s needs.
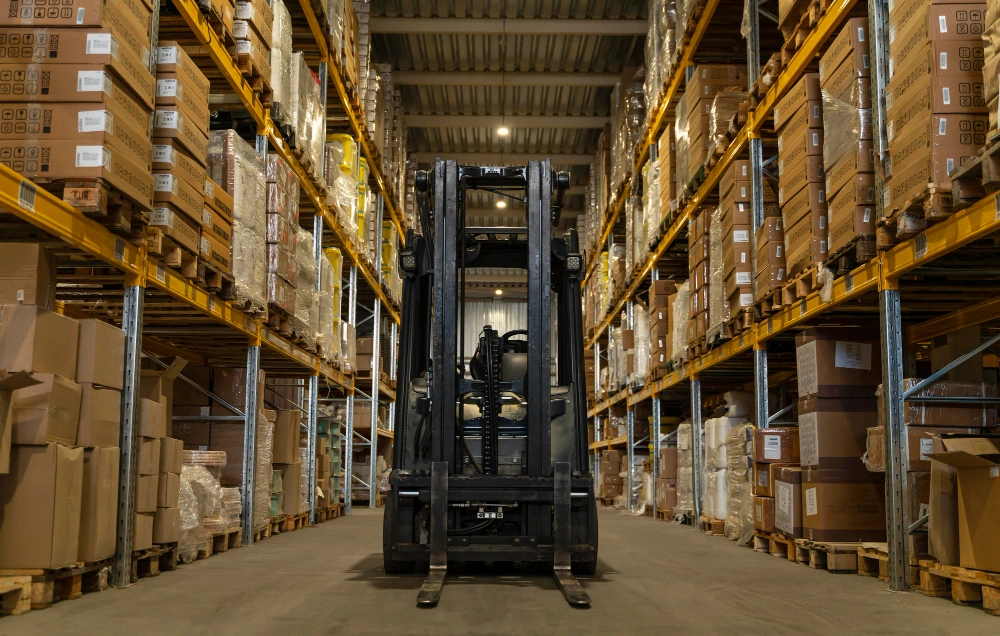
What Lenders Look for in a $5M–$10M Industrial Loan
At this size, industrial lenders underwrite the tenant and the lease as much as the building. Here’s what lenders look for in a $5M-$10M Industrial Loan: tenant credit, lease term vs. loan term, building specs, environmental condition, location and highway access, rents, and the sponsor’s experience and liquidity.
Tenant Strength
Credit or financials of each tenant. For single-tenant and net-lease buildings, the lenders underwrite the tenant as much as the property.
Lease term versus loan term
A lease that expires before the loan matures can trigger a cash sweep or a smaller loan.
Building specifications
Clear height, dock doors, truck access, site plan, and any functional obsolescence.
Leverage and coverage
Typically 65-75% loan-to-value and a 1.25x-1.35x DSCR; conduit lenders also look at debt yield.
Third-party reports
A full appraisal, Phase I environmental report, and property condition report are standard at this size.
Owner-users
SBA 504 can finance a high percentage of the project with as little as 10% down when your business occupies at least 51% of the building.
What to send us
Trailing-12 operating statement, rent roll and lease abstracts, tenant financials, site plan, clear-height and dock data, and a sponsor financial statement with a schedule of real estate owned.
Types of Industrial Property Loans We Offer
We match your industrial property to the right capital source: financial institutions, CMBS, life company, SBA 504, or bridge financing.
Stabilized Industrial Loans
For fully leased warehouses or manufacturing spaces with consistent income streams.
Transitional and Value-Add Loans
Finance capital improvements, lease-up efforts, or re-tenanting projects for underperforming properties.
Bridge to DSCR Industrial Loans
Bridge short-term capital into permanent DSCR-based financing once occupancy stabilizes.
Owner-User Industrial Loans
Ideal for companies seeking to own and operate their facilities while building long-term equity.
Portfolio Refinance Loans
Consolidate multiple industrial or logistics properties for improved management and scalability.
Frequently Asked Questions About Industrial Property Loans
Can I finance both owner-occupied and investment industrial properties?
Yes. REIF Loans offers programs for both investor-owned and owner-user facilities, including warehouses, manufacturing, and logistics assets.
What DSCR is required for industrial loans?
Most lenders require a minimum DSCR of 1.25x, but transitional or bridge options are available for lower ratios with clear improvement plans.
Do industrial properties qualify for long-term fixed-rate financing?
Yes. Many stabilized industrial assets qualify for fixed-rate terms up to 30 years, providing predictable long-term costs.
What documents are needed to apply?
Lenders typically require a rent roll, T-12 financials, lease agreements, and a recent property appraisal.
Can I finance both single-tenant and multi-tenant Industrial properties?
Yes. Transitional and bridge loan programs are available to stabilize the asset before moving into permanent DSCR financing.
What loan sizes do you place for industrial properties?
We place industrial loans up to $10M through banks, life companies, CMBS, SBA 504, and bridge lenders, and can review larger requests.
What is the difference between an SBA 504 loan and a conventional loan for an owner-user warehouse?
SBA 504 can require as little as 10% down and includes a long-term fixed-rate portion, but your business must occupy at least 51% of the building and each owner of 20% or more signs a personal guaranty. A conventional bank loan typically needs more down payment but has fewer program rules.
How long does an industrial loan take to close?
Most $5M-$10M industrial loans close in 60-90 days. Construction, bridge-to-perm, and complex deals can take longer.
What do lenders look at for a single-tenant industrial property?
Tenant credit or financials, the remaining lease term compared with the loan term, renewal options, and what the building would be worth if the tenant left. A lease that expires before the loan matures can reduce the loan amount.
Ready to Finance or Refinance Your Industrial Property?
Whether you’re expanding a warehouse portfolio, acquiring light industrial space, or refinancing a logistics facility, REIF Loans delivers structured financing built for scalability. Explore our financing options for Multifamily, Retail, and Business Loans (SBA).
Our DSCR-based programs, expert advisors, and transparent process ensure fast closings and long-term financial stability.