Explore Grand Rapids DSCR loans investors rely on. Finance or refinance rental property across Kent and Ottawa counties with no income verification, flexible terms, and a lender that underwrites Michigan uncapping and West Michigan rental certification correctly.
At Real Estate Investor Friendly Loans, we help investors build West Michigan rental portfolios with DSCR loans Grand Rapids programs built on property income, not personal income. Whether you’re buying a duplex in Eastown, refinancing a rental near the Medical Mile, or adding units in Wyoming or Kentwood, we make financing simple, fast, and investor-focused.
Michigan is our home state, and Grand Rapids behaves nothing like Detroit despite sharing the same tax law. Prices are higher, millage is roughly half, vacancy is far tighter — and the practical result is that the DSCR ratio here is genuinely competitive rather than automatic.
A Debt Service Coverage Ratio (DSCR) loan allows investors to qualify based on rental property income instead of personal employment or W-2 verification. It’s the preferred choice for investors who want to grow without traditional income barriers.
DSCR Formula:
DSCR = Monthly Gross Rental Income / Monthly PITIA
Grand Rapids Example:
A $265,000 single-family rental collecting $2,050 per month carries roughly $1,356 in principal and interest, $570 in property tax after uncapping, and $158 in landlord insurance — producing a DSCR of 0.98.
That example is deliberate. A DSCR loan Grand Rapids file lands near the 1.00 line far more often than investors expect, because appreciation here has outpaced rent growth. The good news is that the gap is usually small and there are four ways to close it.
DSCR loans Grand Rapids programs are simpler to qualify for than traditional loans. Instead of focusing on personal income, lenders look at property performance and rental stability.
Our advisors partner with top DSCR loan lenders West Michigan investors trust for competitive rates and quick, reliable closings.
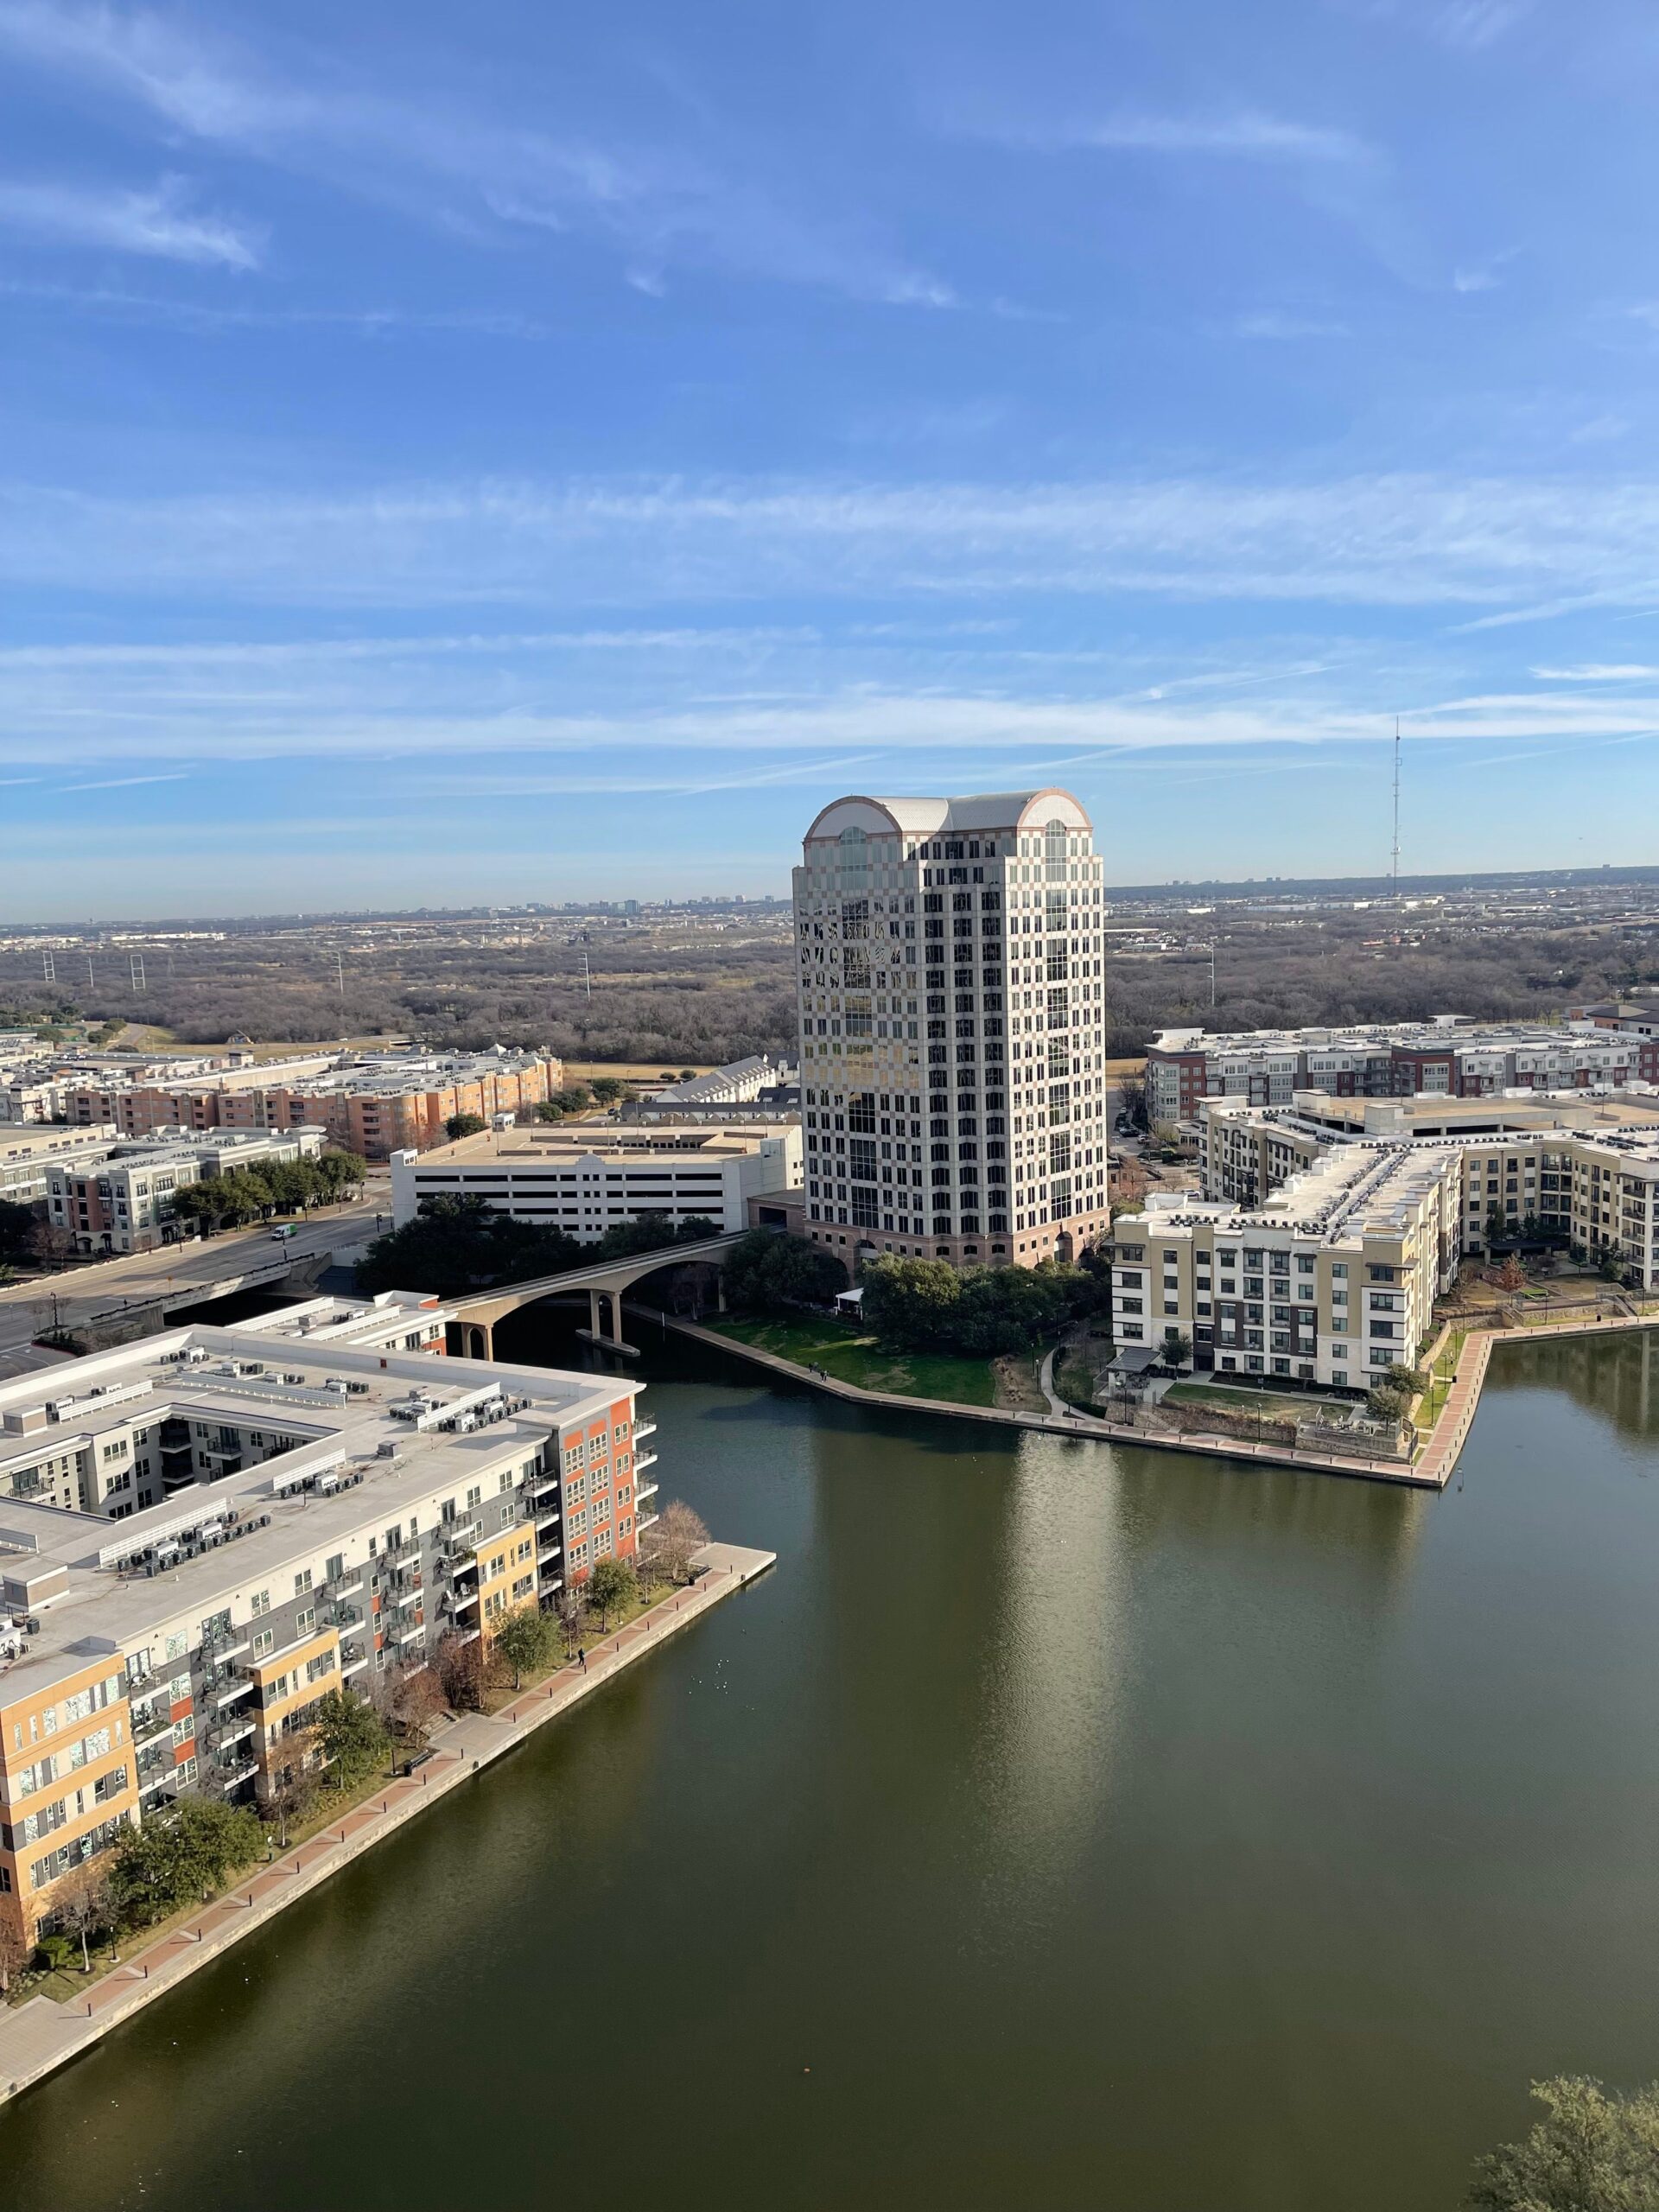
At Real Estate Investor Friendly Loans, we provide a full range of DSCR loans Grand Rapids options for every type of real estate investor.
Use rental income to qualify for new property purchases across Kent and Ottawa counties.
Lower your rate, pull cash out of strong West Michigan appreciation, or refinance to strengthen cash flow.
Qualify using Airbnb or VRBO income. Confirm the property's zoning and city registration status before underwriting STR revenue.
Consolidate several West Michigan doors under one note with a single payment and release provisions for individual sales.
Grand Rapids DSCR home loans make it easier for investors to qualify and scale based on property performance rather than personal income.
Our rental property loans Grand Rapids experts help you compare lenders, programs, and loan terms to choose what fits your portfolio best.
DSCR rates price above conventional owner-occupied financing because the lender takes investor risk without verifying income. In a market where deals sit close to 1.00, the rate you get and the ratio you qualify at are tightly linked — improving one improves the other.
Grand Rapids combines healthcare and manufacturing employment with one of the tightest rental markets in the Midwest — vacancy has been running in the 3 to 4 percent range, well below national levels.
Each area offers different opportunities for DSCR real estate loans Grand Rapids investors.
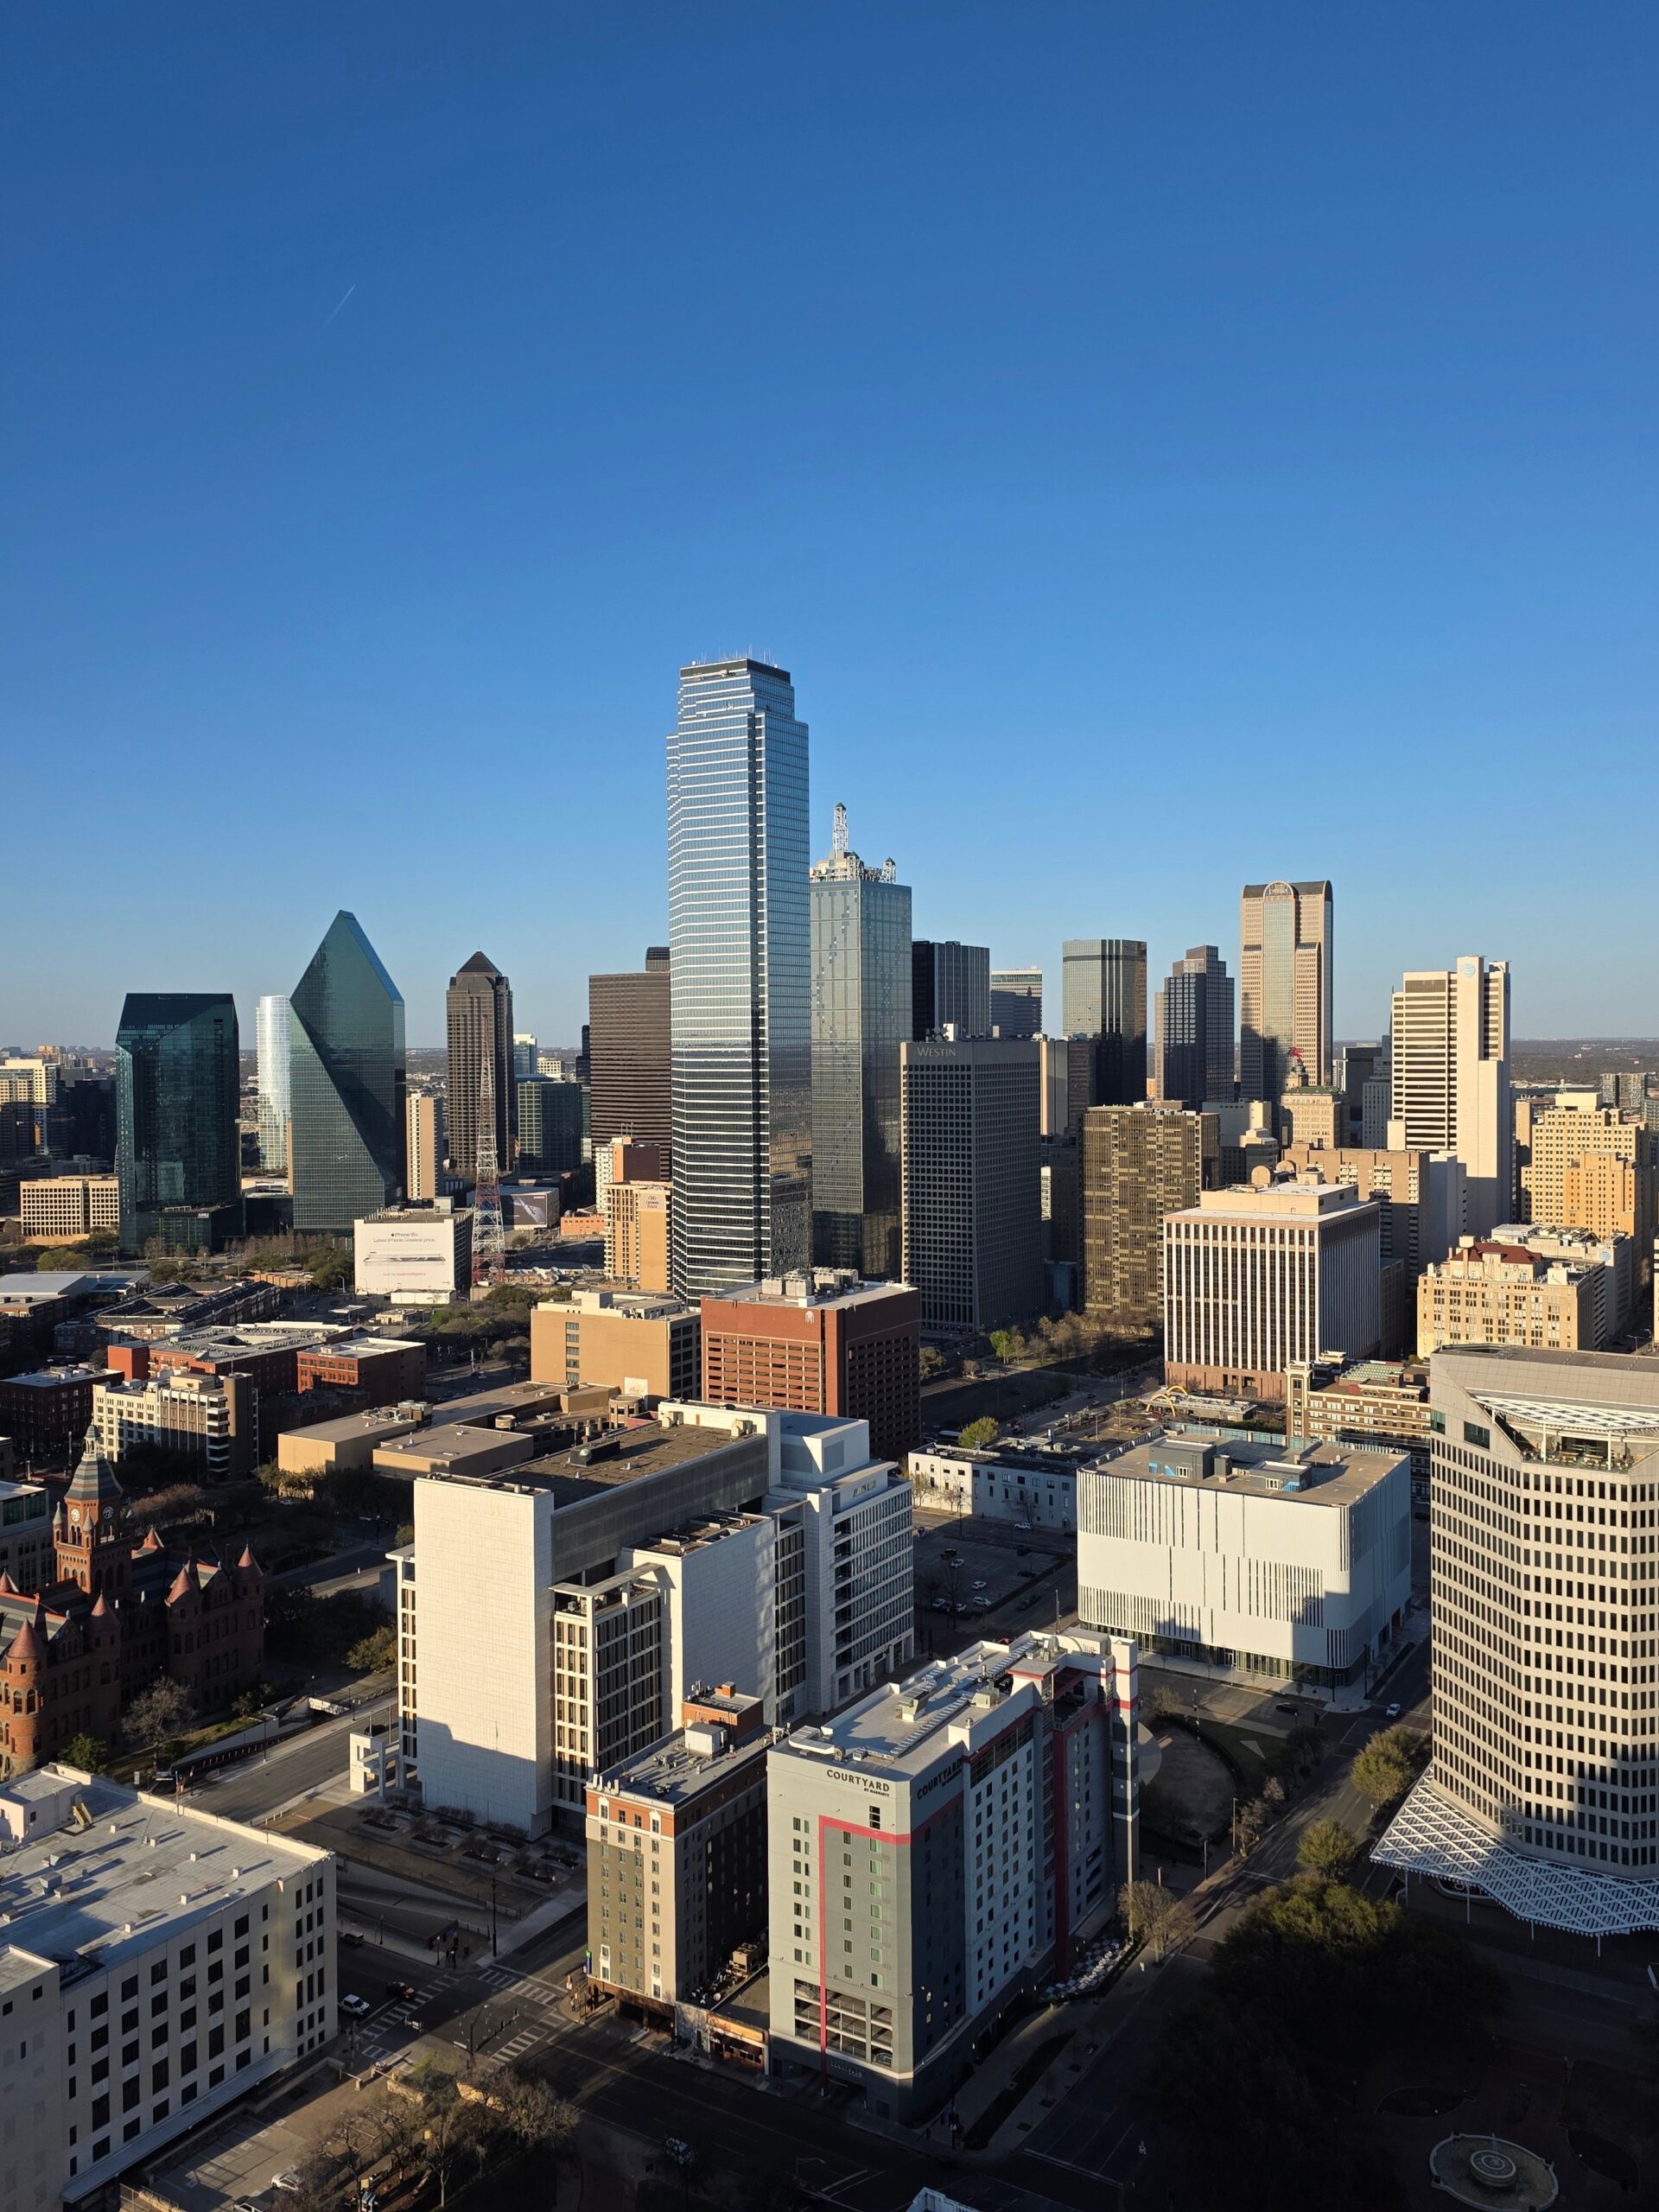
Michigan mechanics apply statewide, but they land very differently here than in Detroit. These three decide most Grand Rapids files.
Michigan caps annual taxable value growth at 5 percent or inflation, whichever is less. But under Proposal A, a transfer of ownership uncaps taxable value in the year following the sale, resetting it to State Equalized Value — roughly 50 percent of market value. Investment property also doesn’t qualify for the Principal Residence Exemption, so you pay up to 18 additional mills of school operating tax. Grand Rapids non-homestead millage runs near 51.6 against a homestead rate closer to 33.6 — so an investor pays roughly 54 percent more than the owner-occupant next door on identical value. Underwrite the uncapped, non-homestead figure.
Grand Rapids operates a Rental Certification Program through Code Compliance. Non-owner-occupied residential property must be registered and inspected, and the city issues a Certificate of Compliance valid for two, four or six years depending on the property’s compliance history — a good record earns a longer cycle. Lead hazard requirements apply to older stock, and non-compliance can bring escalating fines and restrictions on renting. Practically, this is a timeline and budget item: book the inspection early, budget for repairs on pre-1978 housing, and don’t assume rent begins the day you close.
West Michigan’s construction boom has pushed contractor rates up sharply — trades that charged around $75 an hour in 2020 commonly charge $110 to $130 today. Add certification inspections, lead remediation on older stock, and consecutive years of insurance increases, and operators have reported rent growth of roughly 13 percent alongside a net operating income decline of about 5 percent. Institutional owners hold under 1 percent of the city’s rental stock, so these costs land on small landlords. Underwrite maintenance and capital reserves at current West Michigan labour rates, not at what the last owner spent.
Answers to what West Michigan investors ask most before financing a rental property.
Most programs set the floor at 1.00, with better pricing at 1.20 and above. Grand Rapids deals frequently land between 0.95 and 1.10 because appreciation has outpaced rent growth, so the ratio is genuinely competitive here rather than automatic. The upside is that when a deal falls short, the gap is usually small — often under $100 a month — and can be closed with additional down payment, a rate buydown, or a lower-millage community.
Price. Grand Rapids property costs substantially more per dollar of rent than Detroit, which compresses the ratio. Working the other way, Grand Rapids millage runs around 51.6 for non-homestead property against Detroit’s roughly 85, so the tax line is far lighter here — an effective load near 2.6 percent of purchase price versus roughly 4.25 percent. The two effects partly offset, but price usually dominates. The trade is real: Grand Rapids offers a tighter ratio with stronger appreciation and lower vacancy.
Almost certainly. Under Proposal A, a transfer of ownership uncaps the taxable value in the year following the sale, resetting it from the seller’s capped figure to State Equalized Value — roughly 50 percent of market value. Investment property also doesn’t qualify for the Principal Residence Exemption, so you pay up to 18 additional mills of school operating tax that an owner-occupant seller may not have been paying. Underwrite the uncapped, non-homestead figure rather than the seller’s current bill.
The City of Grand Rapids inspects rental properties occupied by someone other than the owner and issues a Certificate of Compliance when the property meets housing code. Certificates run two, four or six years depending on the property, with owners reminded roughly 90 days before re-certification is due. Lead hazard requirements apply to older housing stock. Failing to certify can bring escalating fines and restrictions on legally renting. Schedule the inspection early and budget for repairs, particularly on pre-1978 properties.
Meaningfully. Non-homestead millage inside the City of Grand Rapids runs near 51.6, while surrounding communities in Kent and Ottawa counties sit lower — many in the low 40s or high 30s. On a $265,000 property, the difference between 51.6 and 40 mills is roughly $128 a month, which is often more than enough to move a file from declining to qualifying. Rates vary by school district as well as municipality, so pull the specific parcel rather than assuming a county-wide figure.
By occupancy, yes — vacancy has been running in the 3 to 4 percent range, well below national levels, supported by healthcare and manufacturing employment. The caution is on the expense side: contractor labour costs have risen sharply with the regional construction boom, and operators have reported rent growth around 13 percent alongside a net operating income decline near 5 percent. Strong demand does not automatically mean strong returns. Underwrite maintenance and reserves at current labour rates.
Yes, and most West Michigan investors do. DSCR programs permit vesting in an LLC, corporation, limited partnership or personal name. Entity vesting is one of the primary reasons investors choose DSCR over conventional financing, which generally requires title in a personal name. You will need the operating agreement, articles of organization and EIN at underwriting.
No. DSCR loans require no tax returns, W-2s, pay stubs or debt-to-income calculation. Qualification rests on the property’s rent relative to its full monthly payment, evidenced by an executed lease or a Form 1007 market rent schedule from the appraisal.
640 is the common floor across our lending network, though pricing tiers step meaningfully at 660, 700, 720 and 760. In a market where files sit close to 1.00, credit tier matters more than usual: a better rate lowers your payment, which raises the ratio, which can improve the tier again.
Three to four weeks is typical, with pre-qualification feedback the same day we receive the scenario. Grand Rapids has a practical wrinkle worth planning around: rental certification inspection scheduling and any resulting repairs sit outside the loan timeline but directly affect when the property can lawfully generate rent. Start that process in parallel with underwriting rather than after closing.
At Real Estate Investor Friendly Loans, we specialize in DSCR real estate loans Grand Rapids programs that empower investors to build wealth through real estate. Michigan is our home state, and we underwrite it accordingly.
Send us the address and the expected rent. We’ll model the uncapped non-homestead tax figure, run the ratio, and if it falls short we’ll tell you exactly what closes the gap — before you spend money on an appraisal.